
Why Cotton & Yarn Prices Are Dropping – And How Spinning Mills Can Thrive!
The Indian cotton textile market has witnessed a sustained bearish trend over the recent quarters. Below is the indicative price trajectory for Shankar-6 (the benchmark Indian cotton variety) and 40s Combed Cotton Yarn (40s CWC/Hosiery) over the last six months.
| Month (2026) | Shankar-6 Cotton (₹ per Candy, Ex-Gin) | 40s Combed Cotton Yarn (₹ per kg) |
| April | ~ ₹58,500 | ~ ₹265 |
| May | ~ ₹57,200 | ~ ₹260 |
| June | ~ ₹56,000 | ~ ₹255 |
| July | ~ ₹54,800 | ~ ₹252 |
| August | ~ ₹52,500 | ~ ₹248 |
| September | ~ ₹51,200 | ~ ₹245 |
If you’ve spent any time managing a mill floor over the last two quarters, you know exactly how tight the margins have become.
We are currently witnessing a sustained bearish trend across the Indian cotton textile market. With benchmark Shankar-6 cotton hovering near ₹51,200 per candy and 40s Combed Cotton Yarn struggling at ₹245 per kg, the gap between raw material costs and finished goods realization has narrowed to a razor-thin edge.
But what is fundamentally driving this downward cycle, and more importantly, what actions must we take on the shop floor to protect our operations?
The Logical Reality Behind the Price Drop
The current price depression isn’t just a seasonal fluctuation; it is a compounding of several supply-chain bottlenecks:
-
-
- Sluggish Downstream Demand: Weavers and knitters are purchasing on a strict “hand-to-mouth” basis due to liquidity crunch and delayed payments across the fabric sector.
- Global Export Stagnation: Inflation in major Western markets has dampened apparel retail sales, directly reducing the export orders that feed Indian spinning units.
- The Margin Squeeze: Producing 1 kg of combed yarn currently costs roughly ₹250 to ₹255 (including a ~70% realization rate and ₹45-₹50 in conversion costs). Selling at ₹245/kg means operating at a break-even point or a slight loss, forcing mills to drop prices just to liquidate dead stock.
- The Synthetic Shift: Volatile cotton prices over the past two years forced many fabric makers to permanently adopt poly-cotton or viscose blends, shrinking the baseline demand for 100% cotton.
-
The Action Plan: How Mill Managers Must Respond
In a falling market, relying on high-volume commodity sales is a failing strategy. Survival requires operational agility. Here is the action plan to implement immediately:
1. Pivot to Value-Added Yarns
We must shift a percentage of our ring frames away from highly commoditized counts. Transitioning to compact yarns, slub yarns, or certified organic (GOTS/BCI) can protect margins. If possible, increase the ratio of poly-cotton blends, which offer much better stability during a pure-cotton slump.
2. Strict “Just-in-Time” (JIT) Procurement
Hoarding cotton right now is a fast track to inventory devaluation. Procure raw material strictly to cover pending yarn orders for the next 15 to 30 days. Do not lock up working capital in aging inventory.
3. Calibrate Capacity and Shift Rationalization
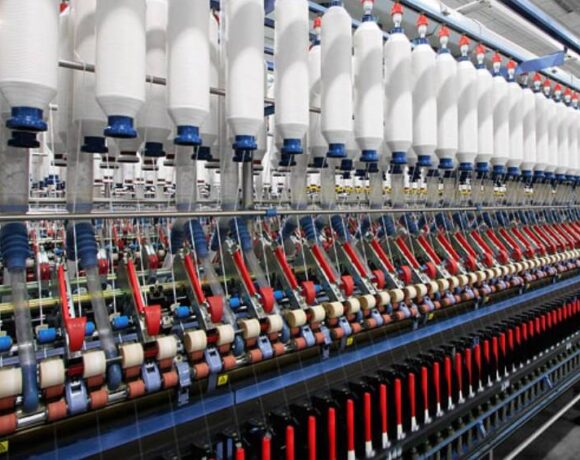
It is far more economical to run a mill efficiently at 80% capacity than to push for 100% and sell the excess yarn at a severe loss. Shut down older, power-heavy ring frames temporarily.
4. Aggressive Variable Cost Control
When market prices are out of our control, internal efficiency is our only shield. Maximize the sale value of comber noils, flat strips, and sweeping waste to the open-end spinning sector. Furthermore, optimize your humidification plant running hours to strictly manage power consumption, our largest conversion cost.
The Bottom Line
Tough markets do not last, but highly optimized mills do. By shifting our product mix and rigorously controlling shop-floor efficiencies, we can weather this pricing storm and emerge stronger when demand inevitably corrects.