
India’s Textile & Chemical Industry: From Market Challenges To The Next Growth Opportunity
How economic growth, global trade agreements and manufacturing competitiveness could shape India’s next industrial growth cycle
By Prem Mishra
A changing business environment
India’s textile and chemical manufacturing industries are approaching an important phase. The past five years have tested manufacturers through volatile raw material prices, higher energy costs, uncertain global demand, intense international competition and pressure on operating margins. Yet the longer-term fundamentals of Indian manufacturing remain encouraging.
India’s real GDP growth was estimated at 7.7% for FY2025–26 in the Central government’s provisional estimates released in June 2026. This provides a supportive backdrop for manufacturing, investment and domestic consumption. Economic growth, however, becomes an industrial advantage only when it translates into productivity, capacity utilisation and competitive products.
Resilience at home, ambition abroad
India’s textile and apparel exports, including handicrafts, increased from ₹2.49 lakh crore in FY2019–20 to ₹3.25 lakh crore in FY2025–26, a compound annual growth rate of about 4.5%, according to provisional DGCIS data reported by the Ministry of Textiles. The journey was uneven: exports rose sharply in FY2021–22, corrected in the following year and then recovered gradually.
In my observation, one of the most encouraging developments is the growing confidence of Indian manufacturers. Many have built strong domestic businesses and are now expanding their international footprint, pursuing new markets and strengthening relationships with global brands. Companies across apparel, home textiles, denim and other segments are demonstrating that Indian businesses can compete on quality, scale, delivery and product development, not price alone. This outward expansion is helping the industry develop the confidence and capabilities needed to compete with established global players.
Trade agreements can widen the opportunity
The conclusion of negotiations for the India–European Union Free Trade Agreement on 27 January 2026 is an important development for exporters. The agreement could improve market access for Indian textile and apparel products, subject to completion of the required legal and domestic procedures before it comes into force. Meanwhile, the India–UK Comprehensive Economic and Trade Agreement entered into force on 15 July 2026, creating preferential access opportunities for Indian exports, including textiles and chemicals.
These partnerships can help diversify export destinations and strengthen India’s position in global supply chains. But tariff advantages alone will not secure orders. Buyers will continue to assess price, quality, compliance, traceability, delivery reliability and environmental performance.
The factory floor will decide competitiveness
The chemical manufacturing sector is an essential partner in this transition. Specialty chemicals, dyes, pigments, textile auxiliaries and performance formulations can help manufacturers deliver differentiated products. At the same time, chemical companies face raw material volatility, global price competition and margin pressure. Long-term growth will depend on innovation, research, application support and the ability to become technology partners, not merely product suppliers.
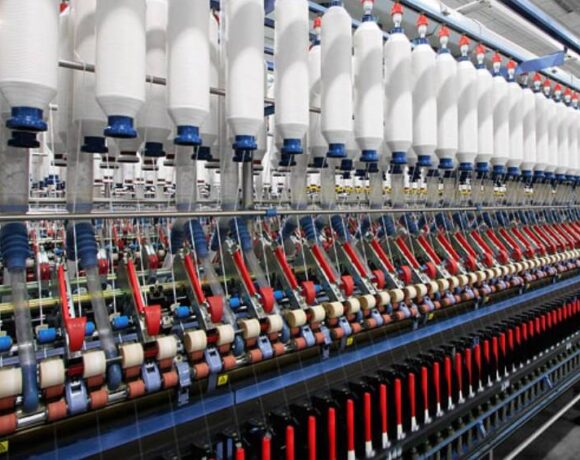
From a manufacturing perspective, I believe the decisive gains will come from microeconomic improvements: lower water, energy and chemical consumption, standardised recipes, reduced reprocessing, better quality control, and higher labour and machine productivity. Enzyme-based processing, optimised pretreatment, efficient peroxide neutralisation and responsible finishing technologies can contribute where they are technically suitable and commercially viable.
Turning potential into sustainable growth
India’s expanding economy, domestic market, manufacturing initiatives and evolving trade relationships create a promising platform for the textile and chemical industries. The opportunity is significant, but a new growth cycle is not automatic. It will require investment in technology, skilled people, infrastructure, compliance and financial discipline—especially among small and medium-sized units.
The next chapter of Indian textile and chemical manufacturing should be about more than producing at scale. It should be about producing efficiently, innovating continuously and competing confidently in global markets.
(Prem Mishra is a Textile Industry Professional & an Independent Consultant)
(Data references: Ministry of Textiles / DGCIS, textile and apparel exports FY2019–20 to FY2025–26 (provisional); MoSPI, Provisional Estimates of GDP FY2025–26, 5 June 2026; European Commission, EU–India FTA negotiations concluded 27 January 2026; Government of India, India–UK CETA effective 15 July 2026)